30-year amortization and the $1.5M insured cap: what changed for BC buyers
On December 15, 2024, two federal mortgage rules changed at once. Insured mortgages, the ones with less than 20% down, became available on homes up to $1.5 million instead of $1 million. And 30-year amortizations on insured mortgages opened up to all first-time buyers and all buyers of newly built homes.
For Metro Vancouver, where a lot of townhouses and family condos sit between $1 million and $1.5 million, the first change matters most. Here's what both mean in dollars.
Change 1: the $1.5 million insured cap
Before December 15, 2024, a home priced at $1 million or more couldn't get mortgage default insurance, so buyers needed at least 20% down. The cap hadn't moved since 2012.
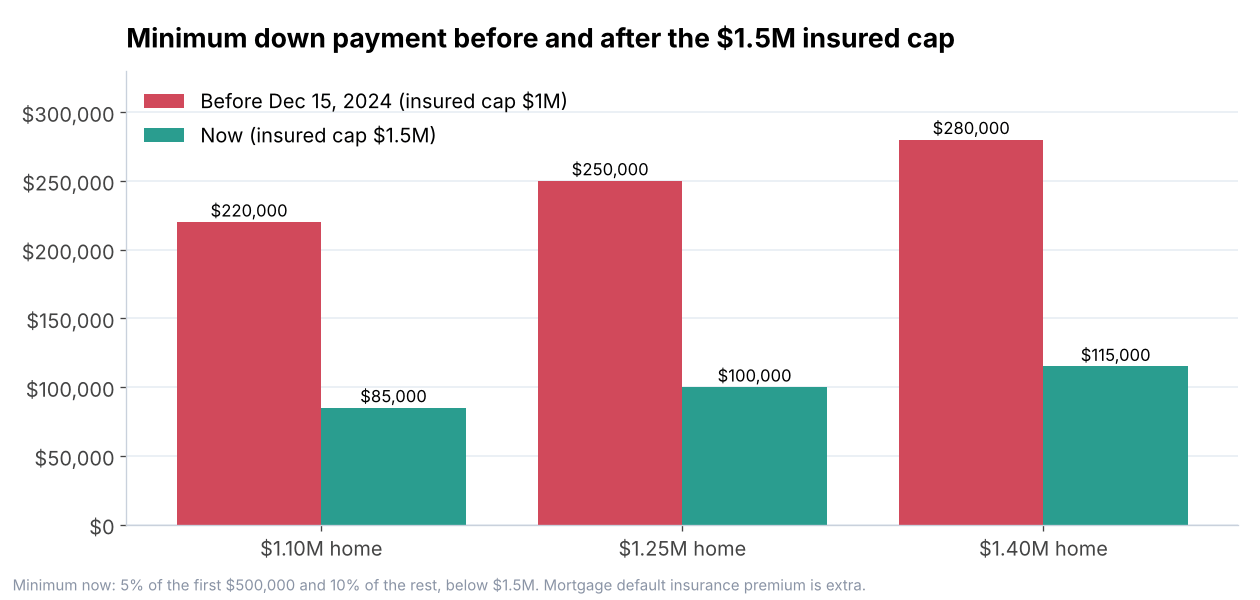
Now, below $1.5 million, the minimum down payment is 5% of the first $500,000 and 10% of the rest.
| Price | Minimum down before | Minimum down now |
|---|---|---|
| $1,100,000 | $220,000 (20%) | $85,000 |
| $1,250,000 | $250,000 (20%) | $100,000 |
| $1,400,000 | $280,000 (20%) | $115,000 |
| $1,500,000 or more | 20% | 20% |
The catch: less than 20% down means a default insurance premium, added to the mortgage. On a big loan that's a large number, and you pay interest on it for decades. Lower minimums make buying possible sooner; they don't make it cheaper.
Change 2: 30-year amortization
Insured mortgages were limited to 25 years. Since December 15, 2024, first-time buyers and buyers of newly built homes can take 30. (Uninsured mortgages, with 20% or more down, could already go to 30 years at most lenders.)
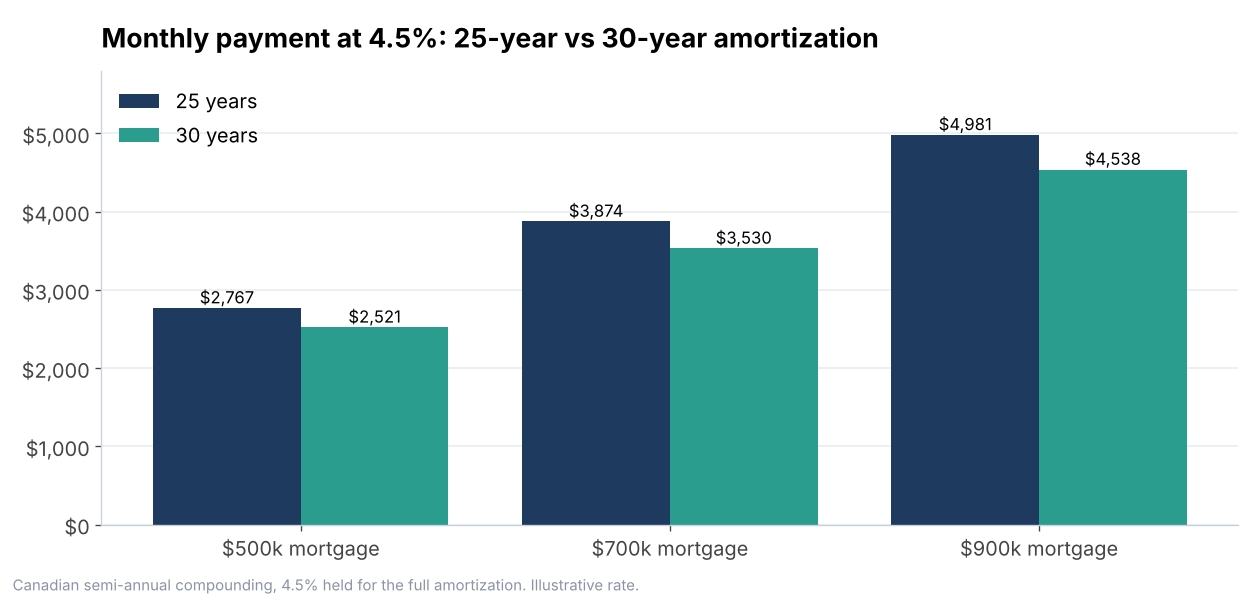
| Mortgage | 25 years | 30 years | Lower payment | Extra interest over the life |
|---|---|---|---|---|
| $500,000 | $2,767 | $2,521 | $246/month | about $77,000 |
| $700,000 | $3,874 | $3,530 | $344/month | about $108,000 |
| $900,000 | $4,981 | $4,538 | $443/month | about $139,000 |
At a constant 4.5%. Real rates will change at each renewal.
The trade is clear: around 9% off the monthly payment in exchange for roughly a quarter more total interest. For many buyers the lower payment is what makes the mortgage qualify under the stress test, which is calculated on the payment.
How to use the longer amortization well
- Qualify at 30, pay like 25. Most mortgages allow 10% to 20% prepayment a year or higher payments. Taking 30 years and voluntarily paying the 25-year amount gives you a cushion if money gets tight.
- Watch the premium. Default insurance premiums are a percentage of the loan; a longer amortization can add a small surcharge. Ask your broker for the exact figure.
- Renewals are the real test. Every five years or so you'll renew at whatever rates are then. A longer amortization leaves more principal outstanding at each renewal.
- Switching lenders at renewal no longer requires passing the stress test again for insured mortgages, which makes shopping around at renewal easier.
For current rate context, see our BC mortgage rates guide.
Checking what you can buy
EstateBlock is a BC real estate search platform that shows sold-price history alongside crime stats, school catchments, flood and climate risk, and transit data on every listing, so you can see what homes between $1 million and $1.5 million actually sell for in the areas you're considering. Sold prices are visible after a free sign-up.
EstateBlock 600 - 777 Hornby Street, Vancouver, BC V6Z 1S4 (888) 428-6808 www.estateblock.com
Sources
- Department of Finance, Government announces boldest mortgage reforms in decades
- Daily Hive, Insured mortgage cap rises from $1M to $1.5M
General information, not financial advice. Payments are illustrative at a constant 4.5%; confirm figures with your lender or broker.